
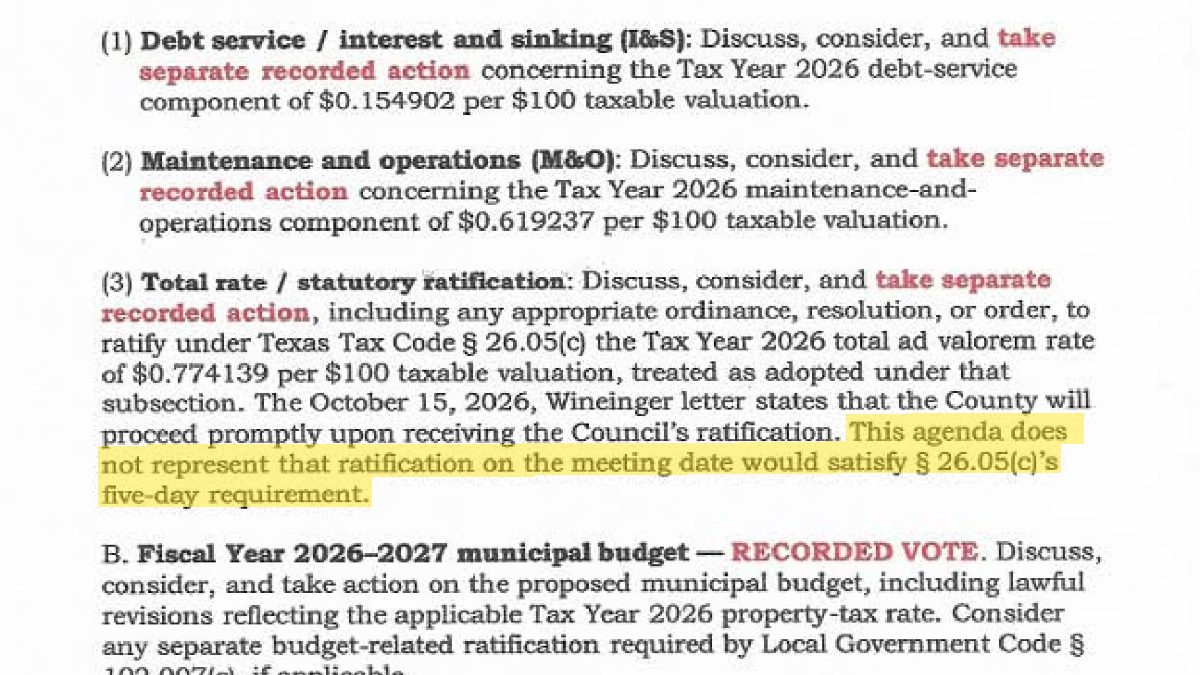
Hawk Cove, Texas, October 27, 2026. The agenda posted for the City Council’s October 28, 2026 special session (6:30 p.m., Judy Fowler Municipal Complex) lists three items of business: the Tax Year 2026 property-tax rate, the budget for the fiscal year that began October 1, and the 2026 tax roll (agenda, pp. 1–2).
The Council has been here before. A motion on the budget or the tax rate died for lack of a second at the meetings of September 22, September 23, September 28, September 29 and September 30 (the budget), October 6 (ratifying a $0.774139 rate) and October 20 (a $0.794903 rate). The recordings are on our Meeting Videos page.
The rate the law already set
When a council does not adopt a tax rate in time, Texas Tax Code §26.05(c) sets one: “the lower of the no-new-revenue tax rate calculated for that tax year or the tax rate adopted by the taxing unit for the preceding tax year.” Hawk Cove’s 2026 no-new-revenue rate is $0.794903 per $100 of value (Notice About 2026 Tax Rates, July 29, 2026). Last year’s rate was $0.774139 (Hunt County Tax Office, 2025 tax rates listing). The lower of the two, $0.774139, is the total on the October 28 agenda.
The same subsection says the council “must ratify the applicable tax rate” “before the fifth day after the establishment” of it. The agenda splits the rate into three recorded votes: $0.154902 for debt service, $0.619237 for maintenance and operations, and ratification of the $0.774139 total, “treated as adopted” under §26.05(c). Then it adds: “This agenda does not represent that ratification on the meeting date would satisfy § 26.05(c)’s five-day requirement” (agenda, p. 2).
The budgets on the board
The Mayor’s letter presenting the proposed FY2027 budget is dated August 28, 2026, and was marked received by the City Secretary that day at 4:48 p.m. It proposed the voter-approval rate of $1.142014 and said: “This year’s balanced budget totals $822,214 across all funds, representing a 13% increase from the previous fiscal year” (photo of the posted letter, p. 1).
A second photo of the same board, undated, shows a signed notice, its signature line titled “Secretary,” saying the version posted August 28 “has been superseded and should not be relied upon,” and “The corrected version supersedes the version posted on August 28” (photo of the board’s right-hand door, p. 2). An FY2027 “Mayor’s Budget Message,” apparently the corrected version, hangs below the notice; its print is too small in the photo to read with confidence, and we hold no other copy of it.
The amended proposed budget, signed by the Mayor with its date line blank, is built on the no-new-revenue rate instead (amended budget, p. 1).
| Mayor’s letter, Aug. 28, 2026 | Amended proposed budget (undated) | |
|---|---|---|
| Tax rate | $1.142014, the voter-approval rate | $0.794903, the no-new-revenue rate |
| Size | $822,214 across all funds, up 13% | $767,863.89 in operating revenue, $804,545.69 in operating expenditures |
| Balanced? | “balanced” | Uses $38,792.80 of beginning fund balance |
| Roads | $27,400 for “current emergency repairs to the city’s streets and roads” | $10,000 |
| USDA sewer loan | $70,440 | $70,440 |
| IRS payroll-tax agreement | not readable in the photo | $42,000 |
Left column: Mayor’s letter, Aug. 28, 2026. Right column: amended budget message, p. 1, and General Fund expenditures, p. 3.
The amended budget against the rate
The amended budget counts $220,479.89 of current-year property tax for the General Fund (revenues, p. 2, line 4010a) and a $53,364 debt levy (p. 1), $273,843.89 in all. That is the $0.794903 rate applied to the City’s 2026 taxable value of $34,449,976 (2026 tax rate worksheet, p. 3, line 22). The rate the law set is lower:
| Amended budget ($0.794903) | Rate set by law ($0.774139) | Difference | |
|---|---|---|---|
| Total levy | $273,843.89 | about $266,691 | about $7,150 less |
| Debt service | $53,364 | about $53,364 (at $0.154902) | none |
| General Fund | $220,479.89 | about $213,327 (at $0.619237) | about $7,150 less |
Our arithmetic: rate × $34,449,976 ÷ 100, rounded. For comparison, the August 28 rate of $1.142014 works out to about $393,424, about $126,700 more than the rate set by law.
The same revenue line brought in $184,276.09 in fiscal 2025 and $188,181.16 in fiscal 2026 through June 30 (p. 2).
The amended budget already draws $28,431.79 of General Fund balance (p. 1). With about $7,150 less in property tax and nothing else changed, that would come to about $35,600, by our arithmetic. The records we hold do not show where the money would go at the rate on the October 28 agenda: neither budget we can read is built on $0.774139, and the only fiscal 2025 report we hold names no outside auditor. The agenda lists the budget for action “including lawful revisions reflecting the applicable Tax Year 2026 property-tax rate” (agenda, p. 2, item 8B).
The “audit” that calls itself a management report
State law requires a city to “have its records and accounts audited annually” (Local Government Code §103.001) and to file its annual financial statement, “including the auditor’s opinion on the statement,” with the city secretary “within 180 days after the last day of the municipality’s fiscal year” (§103.003). Fiscal 2025 ended September 30, 2025, so that was March 29, 2026. On August 3, 2026, the Attorney General wrote that “the City of Hawk Cove did not comply with the requirements under Local Government Code Chapter 103 for fiscal year 2025” (letter, Aug. 3, 2026).
The City has called its 2025 report an audit. A notice posted in about July 2026 read: “The 2025 audit is now complete and will be available for in office viewing” (notice, about July 2026). The City’s fiscal 2025 report is dated May 13, 2026 (report, 13 pages). Here is what that report says about itself:
| What the City calls it | What the report shows |
|---|---|
| “The 2025 audit” | Its cover reads “FY 2025 Internal Year-End Financial Report” and “Internal management report” (p. 1). |
| An audit | “Prepared from the City’s corrected FY 2025 balance sheet, profit and loss statement, and general ledger,” by Karen Fronterhouse, CFO. No certified public accountant, outside accountant or firm is named anywhere in its 13 pages (p. 1). |
| “Internal Auditor Opinion” | The section “Internal Auditor Opinion and Management Summary” begins: “In my opinion, the City’s financial condition reflects continued fiscal strain.” The opinion is about the City’s “financial condition”; §103.003 calls for “the auditor’s opinion on the statement” (p. 1). |
The report is dated 05-13-2026 and marked “Received by City Secretary Angela Massey on 5/13/26,” 45 days after the March 29 deadline in §103.003 (p. 1; signed copy of the same page, p. 13). State law lets a city’s audit be done by its own employee: a city whose books are not audited “by a person prescribed by statute, by charter, or by a person in the regular employ of the municipality shall employ at its own expense a certified public accountant” (§103.002). The report does not say whether its author is an employee or a contractor. At the September 22, 2026 special session, Council Member Rebecca Bernardi put it this way: “we don’t have an audit, we’ve never received an audit” (transcript, September 22, 2026, at about 0:32:50).
Line by line: does the Mayor's budget add up?
The records show a city under financial strain. The City's own fiscal 2025 report, prepared by its CFO, says: "In my opinion, the City's financial condition reflects continued fiscal strain."
- That report lists about $305,000 in federal payroll taxes owed as of September 30, 2025 (p. 8).
- On the same date, the City's main operating account held $1,556.35, out of $156,235.50 across all City bank accounts (p. 8).
- Three IRS federal tax liens against the City, recorded in 2019, 2020 and 2021, have no release in the Hunt County Clerk's index (searched October 27, 2026).
- The Attorney General has determined that the City did not comply with the state audit law for fiscal 2025.
With that much at stake, the budget deserves a close read. We checked each General Fund line in the amended budget against what the City actually spent in fiscal 2025 and in the first nine months of fiscal 2026. Several lines don't hold up.
| Line | What the City spent | FY2027 budget | Why it doesn't add up |
|---|---|---|---|
| Police fuel | $9,003.87 (FY2024); $2,097.10 (FY2025); $72.00 through June 2026 | $72 | That is the nine-month figure carried forward as a full year. If police fuel is now paid from the general fuel line ($5,813.93 through June 2026), the budget doesn't say so. |
| Other police lines (auto, dues, equipment, training) | $39.50, $20.00, $687.15, $51.08 through June 2026 | $39.50, $20, $687, $51 | Five of the seven police lines are the nine-month figures carried over, rounded to the dollar. In all, 11 of the 35 General Fund expense lines match their nine-month figure; four of those are $0. |
| Payroll | $254,534.74 (FY2025); $188,683.70 through June 2026 | $111,131 | About $140,000 below the City's pace through June. The budget message doesn't say any positions are being cut. |
| Payroll taxes | 8 to 10 percent of payroll in each of fiscal 2024, 2025 and 2026 | $26,512 | That is 23.9 percent of the budgeted payroll. At the City's usual 8 to 10 percent, $26,512 in payroll taxes goes with roughly $265,000 to $330,000 in payroll, not $111,131. |
| Trash contractor | $40,809.86 (FY2024); $35,203.60 (FY2025); $0.00 through June 2026 | $0 | The budget still counts $21,197 in trash income. Through June 2026 the City booked $15,429.11 in trash income and no contractor cost on this line. The budget doesn't show where the contractor is paid. |
| Fire department | $3,000.00 (FY2025); $3,774.99 through June 2026 | $0 | The budget message gives no reason. |
| IRS payroll-tax agreement | $0.00 in FY2025 and through June 2026 | $42,000 | That is $3,500 a month. The Mayor's message says the budget "continues to provide" it, but this line shows no payments for 21 months. |
| Disaster (TDEM) income | −$3,465.91 through June 2026 | −$3,466 | It matches, within 12 cents, the $3,465.79 the City's TDEM bank account held on September 30, 2025. The budget repeats it for FY2027; nothing in the record says it will recur. |
FY2027 budget and FY2025-FY2026 columns: amended budget, General Fund expenditures, p. 3 and revenues, p. 2. FY2024: FY2024 year-end report, expense detail. Payroll-tax and TDEM balances: FY2025 report, p. 8. Nine-month figures are the “FY2026 YTD 6/30” column.
Taken together, the amended budget plans about $108,000 less General Fund spending than the City's pace through June (nine months of spending, scaled to a full year). Nothing in the budget says payroll or trash service is ending. The General Fund pages simply don't show which fund will pay for them.
The City has shifted costs between funds before. Its fiscal 2021 budget, a revision dated September 14, 2020, cited a November 2019 "Labor Time Study" and set a "Labor allocation rate - Sewer Fund Allocation to General Fund: 78.41%." Its appendices take $204,000 out of General Fund expenses and add $196,000 to the sewer fund's. In the fiscal 2027 amended budget, the General Fund sends $45,635.45 to the sewer fund, and the sewer fund draws $5,058.74 from its own balance. The Mayor's message adds that "restricted court, child-safety, and sewer customer-deposit balances are not appropriated to balance operations." The sewer, court and debt-service pages that would show where the money lands are not in the records we hold.
A budget is supposed to tell residents what their taxes pay for. Line by line, the pages we hold do not.
Also on the agenda
- The tax roll (item 8C): approval of the 2026 tax roll submitted by Hunt County Tax Assessor-Collector Randy L. Wineinger with his October 15, 2026 correspondence. “The letter requests this as the second of the two Council actions.” Item 8A adds that the letter “states that the County will proceed promptly upon receiving the Council’s ratification.” We do not hold the October 15 letter (agenda, p. 2).
- Two addresses: item 5, “Mayor’s Address to Council,” and item 6, “City Attorney’s Address to Council” (p. 1), and an executive session under Government Code §551.071 for consultation with legal counsel (p. 2, item 9).
- Public comment: “POSTED AGENDA NUMBERED ITEMS ONLY,” three minutes per speaker (p. 1).
The documents
- Agenda, special session, October 28, 2026 (3 pages). What the October 28 votes are. Page 2 has the three rate votes, the five-day sentence, the budget and the tax roll.
- Proposed FY2027 budget as posted at City Hall (2 photos). Page 1: the Mayor’s letter of August 28, 2026, with the $1.142014 rate, the $822,214 total, $27,400 for roads and $70,440 for the USDA loan. Page 2: the right-hand door of the board, undated, with the signed notice that the August 28 version was superseded. The budget tables in both photos are too small to read.
- FY2027 amended proposed budget (4 pages held, undated). Page 1: the Mayor’s message, built on $0.794903. Page 2: General Fund revenues. Page 3: General Fund expenditures. Page 4: the adoption and filing record, every box empty. One handwritten mark on page 2 is covered.
- Notice About 2026 Tax Rates (1 page, July 29, 2026). The $0.794903 and $1.142014 rates and the $53,364 debt levy. One handwritten mark beside the rates is covered.
- 2026 Tax Rate Calculation Worksheet (July 29, 2026). Line 22 on page 3: the $34,449,976 taxable value.
- Hunt County Tax Office, 2025 tax rates listing (2025). Last year’s rate, $0.774139.
- FY2025 Internal Year-End Financial Report (13 pages, May 13, 2026). Page 1: the cover, “Internal management report,” the opinion section and the City Secretary’s received note. Page 13: the same page, signed. The pages between are the City’s balance sheet, income and expense detail and an arrears summary.
- Texas Attorney General letter (1 page, August 3, 2026). The finding that the City did not comply with Chapter 103 for fiscal 2025.
- City notice: “The 2025 audit is now complete” (1 page, about July 2026).
- Local Government Code Chapter 103. The annual audit (§103.001), who may do it (§103.002) and the 180-day filing deadline (§103.003).
- Texas Tax Code §26.05. Subsection (c) is the rate that applies when no rate is adopted in time, and the five-day ratification.
- Meeting Videos: recordings of the September 22, 23, 28, 29 and 30, October 6 and October 20, 2026 sessions, and the September 22 transcript.
Not approved or appreciated by the actual City of Hawk Cove.